
Marco Mencini, Head of Research, Plenisfer Investments SGR
The space economy is often portrayed through its most visible elements: rockets, missions and large satellite constellations. From an economic perspective, however, launch is only the gateway to a much broader value chain. In 2025, the global upstream market, encompassing spacecraft manufacturing and launch services, was worth approximately €75 billion. The downstream market, including satellite communications, Earth observation and navigation services, was worth approximately €490 billion[1]. Growth prospects are significant. According to the World Economic Forum and McKinsey, the global space economy could reach $1.8 trillion by 2035, up from $630 billion in 2023, driven primarily by the spread of space-enabled technologies and services[2].
Most of the space economy already lies in the data and services enabled by orbital infrastructure, which, in order to expand and operate, requires not only new satellites but, above all, launch capacity, sensors, optical systems, ground stations, control software, computing capacity and security systems. The space economy is therefore evolving from a series of projects into a new industrial, digital and strategic infrastructure.
For investors, the implication is clear: identifying a growing market is not enough. They must understand which components will become indispensable, where bottlenecks will emerge and which companies will be able to turn demand into revenue and cash flow.
The new architecture: launch, communications and computing
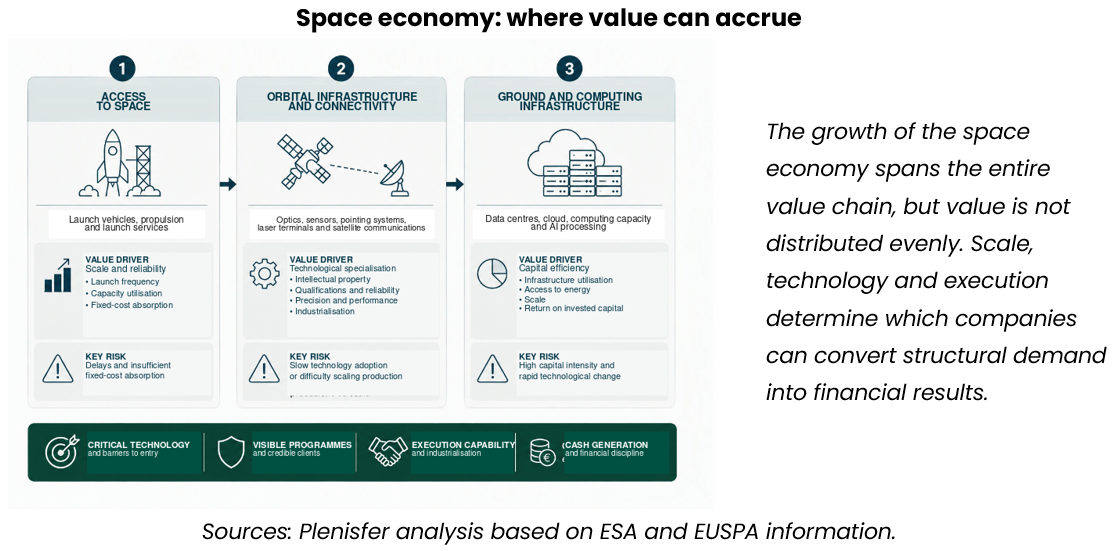
A satellite network consists of three major infrastructure layers. The first is access to space. Launch vehicles and propulsion systems determine the capacity to place satellites and other payloads into orbit. The second layer is orbital infrastructure. It includes satellites, payloads, sensors, pointing systems, advanced optics, communications terminals and inter-satellite links. The third layer is ground and computing infrastructure. It includes gateways, ground stations, networks, cloud infrastructure, data centres and the computing capacity needed to turn satellite data into usable services.
Connecting these layers is the ability to transmit data, both between satellites in orbit and between space and ground infrastructure, and data transmission itself is one of the value chain's potential bottlenecks. Higher sensor resolution, more frequent observations and a growing number of satellites generate increasing volumes of data. Traditional radio-frequency communications remain essential, but spectrum availability and the need to transmit greater volumes of information are driving the development of optical communications, which use light to transfer information. In this area, laser communications represent one of the most important technological advances: for terminals of equal mass and volume, they can offer significantly greater transmission capacity than radio-frequency systems, with advantages in size, efficiency and data-transfer capacity. The greater directionality of laser beams also reduces interference and makes signals harder to intercept.
According to Euroconsult estimates, by 2032 there could be more than 47,000 laser communications terminals operating in orbit, representing a cumulative market value of approximately $6.5 billion[3]. Part of this market remains captive to large, vertically integrated operators that develop and manufacture components directly for their own satellite networks. At the same time, the addressable segment for specialist suppliers is expanding, supported by demand from commercial operators and institutional programmes.
The European Space Agency is developing HydRON, a project designed to demonstrate a multi-orbit optical network integrated with terrestrial networks and capable of terabit-per-second transmission. The objective is to extend into space a data-transport model similar to terrestrial fibre networks[4]. Delivering this performance requires pointing accuracy, optical stability, power consumption compatible with the platforms and the ability to maintain links between moving assets. These characteristics require specialist expertise, qualifications and development timelines that are difficult to shorten.
Where value can accrue
Not all segments of the space economy have the same economic structure. Launch activities, serial satellite manufacturing and satellite network operations require substantial upfront investment. In these segments, returns on capital depend on asset utilisation, mission frequency, process standardisation and the ability to spread fixed costs across growing volumes.
Advanced optics, sensors, laser terminals, pointing systems and mission-critical components can benefit from technological specialisation and barriers to entry linked to intellectual property, reliability, manufacturing precision and customer qualification. In these segments, a company's initial size does not necessarily determine its competitive position. What matters most is the ability to supply a technology that is difficult to substitute within complex programmes. The transition from having a technology available to producing it at industrial scale is therefore one of the decisive factors in value creation.
Long-term drivers
The growth of the space economy is supported by the convergence of four structural trends. The first is the growth of satellite data. Satellites collect information that can be used for environmental, agricultural and infrastructure monitoring, navigation, logistics and emergency management. Artificial intelligence can analyse large volumes of images and data, identify changes and anomalies, and turn raw information into actionable insights. The relationship between space and AI is therefore tangible: the more data is collected, the greater the need for transmission, storage and computing capacity.
The second driver is defence and security spending. In the upstream market, 80% of demand is institutional and is currently dominated by defence. In 2025, European space budgets rose by 12% to €13.5 billion, driven mainly by higher national defence spending[5]. This development supports dual-use technologies that can serve both civilian and military applications. Optical systems, sensors, advanced electronics and communications technologies can be applied across multiple markets, broadening the opportunities for companies able to adapt their expertise to different operating requirements.
The third driver is the pursuit of strategic autonomy. IRIS², the European programme for secure satellite connectivity, envisages a multi-orbit constellation of 348 satellites. The programme aims to provide resilient communications to governments, security and emergency services, businesses and citizens. The implementation agreement was reached in August 2026, and the first launches are scheduled from 2029[6]. Strategic autonomy concerns not only the availability of satellites but also control over the technologies needed for them to operate: electronic components, optical systems, manufacturing capacity, ground infrastructure and communications security.
The fourth driver is communications security. Greater dependence on satellite infrastructure increases the need to protect data and ensure continuity of service. Optical communications, cybersecurity and, in the longer term, quantum technologies may become components of the network architecture. Integrating these technologies into satellite and terrestrial communications could help protect sensitive information and critical infrastructure, including in response to advances in quantum computing capabilities. ESA notes that satellites could help distribute secure communications across continental distances[7].
These four drivers can support multi-year programmes and fuel demand for space infrastructure, communications and computing capacity. It is along this value chain that we are identifying investment opportunities.
Investment opportunities
This evolution is creating opportunities across several segments of the value chain, each with different industrial characteristics and economic profiles. The first area comprises companies active in launch vehicles and propulsion systems, which provide access to orbit. The second comprises companies specialising in advanced optics, sensors, pointing systems and satellite communications. The third area is computing infrastructure: satellite data only acquires value when it is processed and transformed into applications.
Investment opportunities therefore require a selective approach, focused on companies operating in value-chain segments that are set to become more important as orbital infrastructure expands. The selection process considers several factors: intellectual property and technical qualifications, customer concentration, the duration and funding arrangements of current programmes, the ability to convert orders into actual revenue and industrialise production, capital requirements and cash-generation capacity. The selection process must also consider the associated risks of potential exposure to government space and defence programmes: changes in public-spending priorities, budget cuts or shifts in national and European policies may delay or reduce funding for sector companies' existing and future projects.
Throughout this process, valuation remains central. A structural trend does not justify any price, especially in businesses characterised by long programmes, high capital intensity and significant execution risk. For investors, the challenge is to identify companies that provide technologies and services essential to the development of the space economy and can translate that position into sustainable revenue, margins and cash flow.
[1] Source: European Space Agency, ESA Space Economy Report 2026, 13 July 2026.
[2] Source: World Economic Forum and McKinsey & Company, Space: The $1.8 Trillion Opportunity for Global Economic Growth, April 2024.
[3] Source: Plenisfer Investments analysis based on Euroconsult estimates and market data on laser communications. The forecasts shown are estimates, not realised results.
[4] Source: European Space Agency, HydRON – High Throughput Optical Network Demonstration System, 2025.
[5] Source: European Space Agency, ESA Space Economy Report 2026, 13 July 2026.
[6] Source: European Union Agency for the Space Programme, Commission accelerates IRIS² deployment with enhanced security and expanded satellites network, 7 August 2026.
[7] Source: European Space Agency, Quantum Technologies.
Disclaimer
This analysis relates to Plenisfer Investments SGR S.p.A. (“Plenisfer Investments”) and does not constitute a marketing communication relating to a fund, an investment product or investment services in your country. This document does not constitute an offer or invitation to sell or purchase securities or any assets or businesses described herein and does not form the basis of any contract. Any opinions or forecasts provided are as of the specified date, are subject to change without notice, do not predict future results and do not constitute a recommendation or offer of any investment product or service. Past performance is not indicative of future returns. There can be no guarantee that any investment objective will be achieved or that capital will be returned. This analysis is intended exclusively for professional investors in Italy pursuant to Directive 2014/65/EU on markets in financial instruments (MiFID). It is not intended for retail investors or U.S. Persons, as defined in Regulation S of the United States Securities Act of 1933, as amended. Information is provided by Plenisfer Investments, authorised as a UCITS management company in Italy and regulated by the Bank of Italy – Via Niccolò Machiavelli 4, Trieste, 34132, Italy – CM: 15404 – LEI: 984500E9CB9BBCE3E272. All data used in this analysis, unless otherwise stated, are provided by Plenisfer Investments. This material and its contents may not be reproduced or distributed, in whole or in part, without the express written consent of Plenisfer Investments.
Plenisfer Investments SGR S.p.A.
Via Niccolò Machiavelli 4
34132 Trieste (TS)
Via Sant'Andrea 10/A, 20121 Milano (MI)
info@plenisfer.com
+39 02 0064 4000
Contact us at info@plenisfer.com
Tax ID: IT 01328320328
Belonging to Generali Italian VAT group: 01333550323
Registered to The National Compensation Fund
This is a marketing communication. Please refer to the Prospectus and Key Investor Information Document (KIID/KID) before making any final investment decisions. Past performance is no indication of future performance.
The value of your investment and the return on it can go down as well as up and, on redemption, you may receive less than you originally invested.
© Copyright Plenisfer Investments onwards 2020. Designed by Creative Bulls. All rights reserved.